I'll give you my real number on day one.
I price your file the way an underwriter is going to read it, because for years that was my job. The number I open with is the number I intend to close at.
- $121M
- Originated, verifiable on Modex
- ~$750M
- Processed before I originated
- 200+
- Lenders through Loan Factory
- CA + OR
- States I'm licensed in
I don't have a specialty. That's deliberate.
Last year I closed first-time buyers, home equity, an FHA refinance, conventional investment properties, DSCR purchases and refinances, and a fix-and-flip.
That range is the point. When you've priced enough different files, you stop guessing about where a new one belongs.
Start where you actually are.
Your home
Investors and self-employed
- Investment propertyIt needs to pencil. Everything else is decoration.
- Fix and flipCertainty on timeline matters more than almost anything else.
- Self-employedYour tax returns don't show what you actually make.
Want to check the math before we talk? Run the numbers yourself: DSCR, refinance break-even, and keep-your-first vs cash-out.
Three things you can hold me to.
The real number first
I'd rather open with something I can stand behind than something that sounds good on a first call.
I'll tell you when it's no
If your file doesn't work right now, I'll say so and tell you exactly what would have to change. That's faster than optimism.
Check my pricing before you call
Loan Factory publishes its pricing publicly and updates it continuously. It's the same engine I quote from.
For years my job was finding out why loans wouldn't close.
Camaron Ordonez, after about $750M in loans processed
What clients have said.
“He is incredibly prompt, professional, and consistently goes above and beyond to gather the necessary information and ensure everything stays on track. … he helped us close the new loan before the next payment on the old loan was due, which required careful coordination and strong attention to detail.”
“As first-time home buyers, we were grateful for the support from Cam and Wade, who managed to meet some very tight deadlines and answered all our questions while guiding us through the entire loan process from the beginning to the end of escrow.”
“He was an amazing communicator and always follows up with my questions and concerns from my loan application until I close escrow and had my new home keys given. … He was very transparent from the beginning til end.”
“Working with Camaron was great and we highly recommend him. He was honest and helpful to get us started in getting the preapproval for a home started.”
“Absolutely great to work with Cam. Very knowledgeable in the mortgage domain.”
Twenty minutes, no obligation.
Tell me what you're trying to do and I'll tell you what's actually possible. If I'm not the right person for it, I'll say that too.
I used to be the reason loans didn't close.
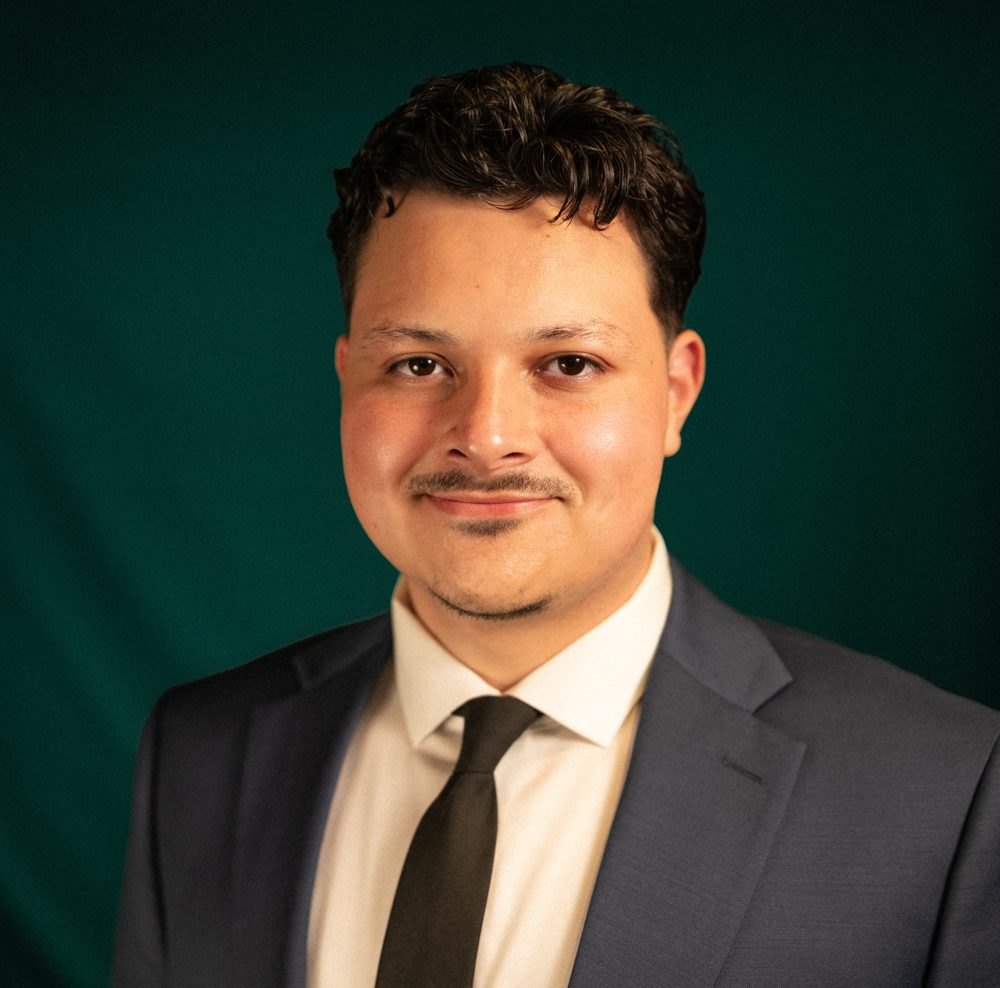
I've originated $121 million in mortgages. You can verify that on Modex. It's third-party data, not a number I made up for a website.
The part that matters more is what came before it. For several years I was a processor. My job was to take other people's loan files and get them through underwriting, which mostly meant finding out why they wouldn't make it. Roughly $750 million in loans crossed my desk that way.
That background changes how I quote. Most of the work of pricing a file is anticipating what an underwriter will find in it. I've spent years on that side of the desk, so my opening number isn't optimism. It's a finished read.
I originate through Loan Factory, Inc., which gives me access to 200+ lenders and publishes its pricing publicly. I'm licensed in California and Oregon.
I don't specialize. Last year I closed first-time buyers, home equity, FHA, conventional investment, DSCR, and a fix-and-flip. Moving between borrower profiles keeps me sharp, and it means I've probably seen your situation before, even if it feels unusual to you.
Start where you actually are.
Six starting points. Each tells you what I'd need to look at and what you get out of a first conversation.
Your home
Investors and self-employed
- Investment propertyIt needs to pencil. Everything else is decoration.
- Fix and flipCertainty on timeline matters more than almost anything else.
- Self-employedYour tax returns don't show what you actually make.
Want to check the math before we talk? Run the numbers yourself.
Everyone is talking at once and none of them agree.
Your agent has an opinion. Your parents have a different one. A coworker who bought in a completely different market has the strongest opinion of all. Meanwhile, you're trying to work out whether you can do this at all, and nobody has walked you through the mechanics.
My clients tell me the education is the part that mattered. Not because the process is complicated once you see it, but because nobody had laid it out in order before. So that's how I start: what happens, in what sequence, what you control and what you don't.
There are several loan programs built specifically for buyers who haven't owned before, and they carry real trade-offs against each other. Which one fits depends on your credit profile, how long you plan to hold the property, and how much cash you want to keep in reserve. That's a conversation, not a web page.
What I'd want to look at
- Your credit profile, and whether it's worth improving before you buy
- Income, and how it's documented
- What you have available in cash and reserves
- Where you're looking, and your timeline
On the first call I'll tell you what's realistic and, if it isn't yet, exactly what would change that.
You need the cash. You don't want to touch your first mortgage.
If you financed or refinanced a few years ago, the loan you're sitting on may be considerably better than anything available today. Refinancing the whole thing to access equity would mean giving that up. That's usually the wrong trade, and it's the first thing I check.
There are ways to access equity while leaving your existing first mortgage exactly where it is. A HELOC and a fixed second work differently from each other, and which one fits depends on whether you need a lump sum or ongoing access, how long you need it for, and what you're using it for.
The math here is usually decisive rather than ambiguous. Once I see the actual numbers the right answer tends to be obvious. Sometimes the right answer is to do nothing, and I'll tell you that too.
What I'd want to look at
- Your current loan: balance, term, and when you took it out
- An estimate of what the property is worth now
- How much you need, and whether it's once or ongoing
- What you're funding, and over what horizon
Want a first read on your own? Compare keeping your first mortgage vs a cash-out refinance.
It has to pencil. Everything else is decoration.
You're not shopping for a house, you're underwriting an asset. What you need from a broker is speed, accurate pricing, and someone who doesn't need the property explained to them.
Conventional financing on an investment property works differently from a primary residence, and DSCR lending works differently again: it qualifies the property on its own income rather than qualifying you on yours. Which route is better depends on how many units are in the portfolio, what your reporting looks like, and how you're structuring ownership.
Last year I closed two conventional investment purchases, a DSCR purchase, and a DSCR refinance. I'm comfortable in this lane and I won't slow you down learning it.
What I'd want to look at
- The property, unit count, and rent roll or market rent estimate
- How you're holding title, personally or in an entity
- What else is in the portfolio
- Your timeline, and whether you're already in contract
Running a deal now? Check the DSCR on it before we talk.
Your real risk is the calendar.
On a flip, financing that arrives late is worse than financing that costs slightly more. You're carrying the property, the crew is scheduled, and the exit assumptions were built around a date. So the first question I ask is whether the timeline is actually achievable, not whether I can theoretically get it done.
Bridge and construction lending, vacant-lot financing, and rehab draws all behave differently from a standard purchase loan, both in how they fund and in what the lender wants to see before each stage releases. Knowing where those friction points are in advance is most of the job.
If the timeline you need isn't realistic with a given structure, I'd rather tell you on the first call than discover it in week three.
What I'd want to look at
- The property and your scope of work
- Your budget and how you've phased it
- Your experience: how many of these you've done
- Your exit plan and target date
Your tax returns don't show what you actually make.
You write off everything your accountant tells you to write off, which is the correct thing to do right up until you apply for a mortgage. Then the same return that saved you money makes you look like you barely earn.
There are loan programs built for exactly this. Bank statement loans look at deposits rather than net income. Asset-qualifier loans look at what you hold rather than what you report. They price differently from a conventional loan and they aren't the right answer for everyone. They exist because this problem is common, not exotic.
Whether one of them is right for you depends on numbers I'd need to see. Once I do, this is usually a quick answer.
What I'd want to look at
- 12 or 24 months of business or personal bank statements
- What the business does, and how long you've been doing it
- Whether the property is a primary residence, second home, or investment
- What you're trying to accomplish, and by when
I'll tell you on the first call whether this works and roughly what the trade-off is against a conventional loan.
The honest question is whether it's worth doing at all.
Plenty of people should not refinance right now, and I'll tell you if you're one of them. A refinance only makes sense if what you gain outweighs what it costs you to get there, and how long you plan to keep the property is usually the variable that decides it.
There are also several distinct kinds of refinance that get talked about as if they were one thing: rate-and-term, cash-out, and the streamlined programs available on FHA, VA, and USDA loans, which have their own qualifying rules. They're not interchangeable, and starting with the wrong one wastes weeks.
This is a math problem with a real answer. Bring me your current loan and I'll run it properly rather than guess.
What I'd want to look at
- Your current loan: type, balance, term, and when you took it out
- How long you plan to keep the property
- Whether you need cash out, or just better terms
- What's changed in your income or credit since you closed
Want a first read on your own? Find your refinance break-even.
Run the numbers yourself.
Three quick calculators for the questions I get most from investors and homeowners. Use your own numbers, including the rates you've been quoted. These are estimates for a first read, not a quote.
Refinance break-even
How many months until the payment savings cover the cost of refinancing?
DSCR check
Does the rent cover the full payment? DSCR loans qualify the property on this ratio instead of your personal income.
Keep your first, or cash-out refinance?
If you add a second loan (HELOC or fixed second) on top of your current mortgage, what's your combined rate compared with refinancing everything?
Estimates only. Payments shown are principal and interest unless noted, use only the numbers you enter, and are not a quote, loan approval, or offer of credit. Your actual rate and terms depend on your full file, property, and lender guidelines. For live pricing, see Pricing.
I don't publish rates here. Here's where to find mine.
A rate posted on a website is out of date by the time you read it. And a rate quoted without your credit profile, property type, occupancy, and loan structure isn't really a rate. It's a guess with a decimal point.
So rather than post something stale, I'll point you at the live version.
I originate through Loan Factory, Inc. They publish live pricing publicly, updated continuously, filterable by loan purpose, loan type, and state. It's the same pricing I'm working from when I quote you.
Heads up: The link below leaves my site and opens Loan Factory's. That's my brokerage, and their platform is where pricing and applications live.
Before you click, here's what happens next.
I originate through Loan Factory, Inc. (NMLS #320841). They're my brokerage. Their platform runs the secure application and document upload, so that part of the process lives on their site rather than mine.
When you click below you'll land on Loan Factory's application with my name on it. That's expected, not a redirect gone wrong. Everything else, from strategy to pricing to follow-through, is me.
Most people should book a call first. The application is more useful once we've established which loan you're actually applying for.
Twenty minutes. No obligation, no cost.
Tell me what you're trying to do and I'll tell you what's actually possible, including if the answer is that you should wait, or that I'm not the right person for it.
Prefer to book right here? The scheduler is run by Calendly. It only loads when you ask for it, and Calendly may set its own cookies once it does.
Get in touch.
- Phone
- (408) 757-3228
- Licensed in
- California and Oregon
- Based in
- San Jose, CA
The fastest way to get a real answer is to book twenty minutes.
Privacy policy
This policy covers camdoesloans.org, the personal website of Camaron Ordonez (NMLS #1994381), a mortgage broker originating through Loan Factory, Inc. (NMLS #320841). It explains what this site collects, why, and the choices you have.
What this site collects
- What you send me. If you fill out a questionnaire on this site, I receive what you enter: your name, phone, email, and your answers about your project (for example property use, budget range, approximate credit range, and how you document income). I don't ask for Social Security numbers, account numbers, or documents here.
- Booking a call. If you book through the scheduler, Calendly collects the details you enter and shares them with me.
- Basic server logs. The site's host, Netlify, processes standard technical data such as IP address and browser type to deliver and secure the site.
- Calculators. Numbers you type into the Run the numbers calculators stay in your browser. They are not sent or saved.
Cookies and tracking
This site doesn't set cookies and doesn't use analytics, advertising pixels, or tracking scripts. Fonts are served from this site, not from a third party. If you choose to load the Calendly scheduler on the Book page, or click through to Calendly, Loan Factory, or social media sites, those services may set their own cookies under their own policies.
How I use your information
- To respond to your inquiry, follow up by phone, text, or email as you agreed, and help with your financing.
- If you apply, your loan is handled through Loan Factory, Inc. and its platform, under Loan Factory's privacy notice.
- To keep records as required by law.
Who it's shared with
I share your information only with service providers that run this site and my business (Netlify for hosting and form delivery, Calendly for scheduling, Google Workspace for email), with Loan Factory, Inc. as my brokerage, and with lenders or others only as needed to work on your loan or as required by law. I don't sell or share your personal information for cross-context behavioral advertising.
Your choices and California rights
You can ask me what personal information I have about you, ask me to correct it, or ask me to delete it, subject to legal record-keeping requirements. You can stop calls or texts at any time by telling me or replying STOP. Because this site doesn't sell or share personal information, there is nothing to opt out of on that front. Some records tied to a loan application are governed by federal financial privacy law (GLBA) and Loan Factory's privacy notice.
Security
The site is served only over HTTPS, and forms submit directly to the site's host. Please don't send sensitive documents or account numbers through the website or by email; I'll give you a secure upload link through Loan Factory when it's time.
Contact
Questions or requests: info@camdoesloans.org or (408) 757-3228.